Refurbishment and investment
Property refurbishment costs: when is the work worth it?
Before replacing a kitchen or planning a full refurbishment, establish what the property needs and what the work will achieve. Every pound spent should have a clear purpose in your investment plan.
Buy well, then decide what needs doing
One of the points I make to investors is to question spending that the property does not need. A functioning kitchen may need repairs or a refresh. It does not automatically need replacing because you would choose something different for your own home.
The question is practical: will the work make the property safe, resolve a defect, improve its suitability for tenants, reduce future costs or add value that the evidence supports? If the answer is unclear, investigate before committing the money.
That is a useful discussion to have with a property mentor, your surveyor and a local letting agent. Each brings a different part of the evidence.
Separate necessary work from optional upgrades
Start with the building and the people who will live in it. Safety, sound repair and the requirements that apply to the property take priority. Avoiding unnecessary expenditure must never become an excuse for leaving hazards or essential repairs unresolved.
The GOV.UK repairs guidance explains important landlord responsibilities. Ask appropriately qualified contractors to investigate defects and specify the work. A fresh coat of paint cannot resolve the cause of damp or structural movement.
- Essential work: repairs, safety matters and work needed to meet the requirements that apply to the property.
- Useful investment: work supported by tenant demand, reduced maintenance or credible evidence of added value.
- Optional spending: cosmetic changes driven mainly by personal taste, with little evidence of an investment benefit.
The same item can fall into different categories in different properties. The condition of the existing kitchen matters more than a standard refurbishment package.
Test the payback on an optional improvement
Ask a local agent whether a proposed improvement would change the achievable rent, tenant demand or likely sale price. Then compare that benefit with the full cost, including any additional time without rental income.
Illustration: an optional £6,000 kitchen that increases rent by £50 a month produces £600 a year of additional gross rent. The simple payback is 10 years, before finance, tax, maintenance and periods without rent. If the rent does not rise, there is no rental payback on that basis.
That does not settle every decision. A replacement may reduce repeated repairs, improve usability or help the property let more reliably. Put those reasons in the appraisal instead of assuming that all refurbishment creates a profit.
Get a complete scope and realistic quotations
Give contractors the same written schedule so their quotations can be compared. Establish what is included, what is excluded, whether VAT applies, the proposed timetable and how changes will be approved.
Budget for more than the visible finishes. Waste removal, access, professional reports, approvals, utilities, insurance and the time spent holding an empty property can affect the result. Agree payment stages against clearly defined progress.
Our property refurbishment service in Liverpool and Wirral connects the planned work with the property’s intended use. An appropriate survey helps identify issues before a contractor prices the cosmetic work.
Check the purchase price before relying on a refurbishment
Even well managed work cannot rescue every acquisition. Start with a realistic completed value, deduct the full purchase and renovation costs, and allow for uncertainty. The margin must make sense before you buy.
Our Methuen Street case study recorded a £75,000 purchase and a later £120,000 valuation without a refurbishment. It illustrates the importance of the original purchase price. The valuation was a historical assessment, not a realised resale profit or a result every property can reproduce.
A different example is Alexander’s Wallasey refurbishment case study. Read the purchase, works and valuation figures together. The useful lesson is to match the amount of work to the opportunity.
Allow for a slower or more expensive project
Run the figures again with higher renovation costs, a delayed letting date and a lower rent or resale value. Keep an accessible contingency that suits the condition of the building and the uncertainty in the quotations.
For a resale project, our guide to flipping property at auction shows how the exit price and holding costs affect the maximum bid. For a rental property, establish the ongoing management arrangements before the work finishes.
A property mentor should challenge the spending
Useful mentorship includes asking why you want to do the work, what evidence supports the benefit and whether your funds would be better retained for essential repairs or another purchase. It should help you make that judgement with confidence.
Dominic Farrell works with investors on acquisition decisions, due diligence and the practical investment plan. Explore the Property Auction Professional Mentorship for the programme details, or use our property investment checklist to organise your next appraisal.
About Dominic Farrell
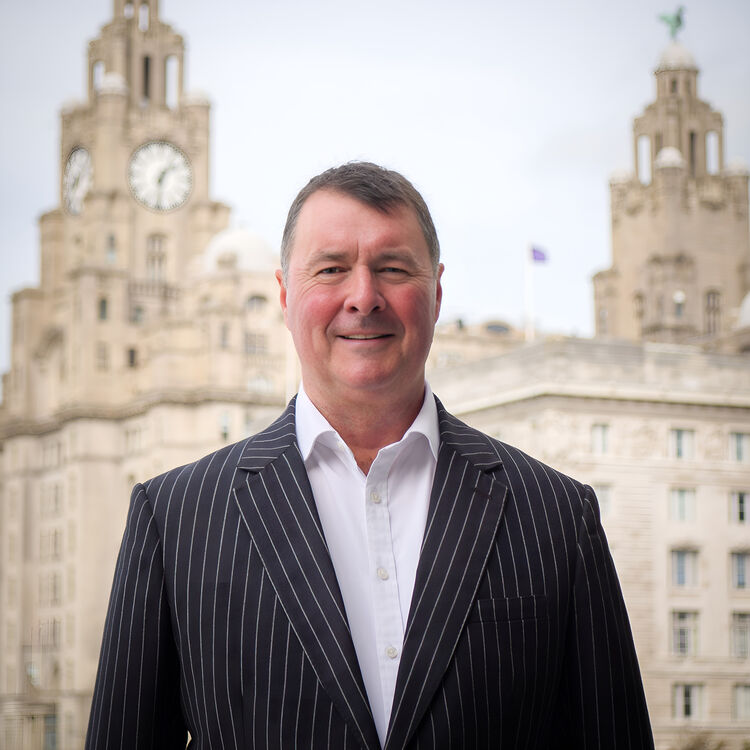
Dominic is a property investor, developer and mentor, a director of Tuna Fish Property, author of Property Auctions: Repossessions, Bankruptcies and Bargain Properties and host of The Property Auctions Podcast. Explore his experience and approach to property mentorship.
Build the judgement behind your next purchase
Discuss your objectives, experience and investment plans with Dominic Farrell. Explore whether the Property Auction Professional Mentorship, delivered through Distressed Assets, is appropriate for you.
Refreshed from the original Tuna Fish article. Illustrative calculations are examples, not forecasts. Assess the property and obtain legal, tax, lending and surveying advice appropriate to your transaction.