A successful refurbishment starts with the price you pay and the plan you make before work begins. For investors considering property refurbishment in Liverpool and the wider Merseyside area, Alexander Rosenthal’s purchase in Wallasey offers a useful example of how buying, improving, letting and refinancing can work together.
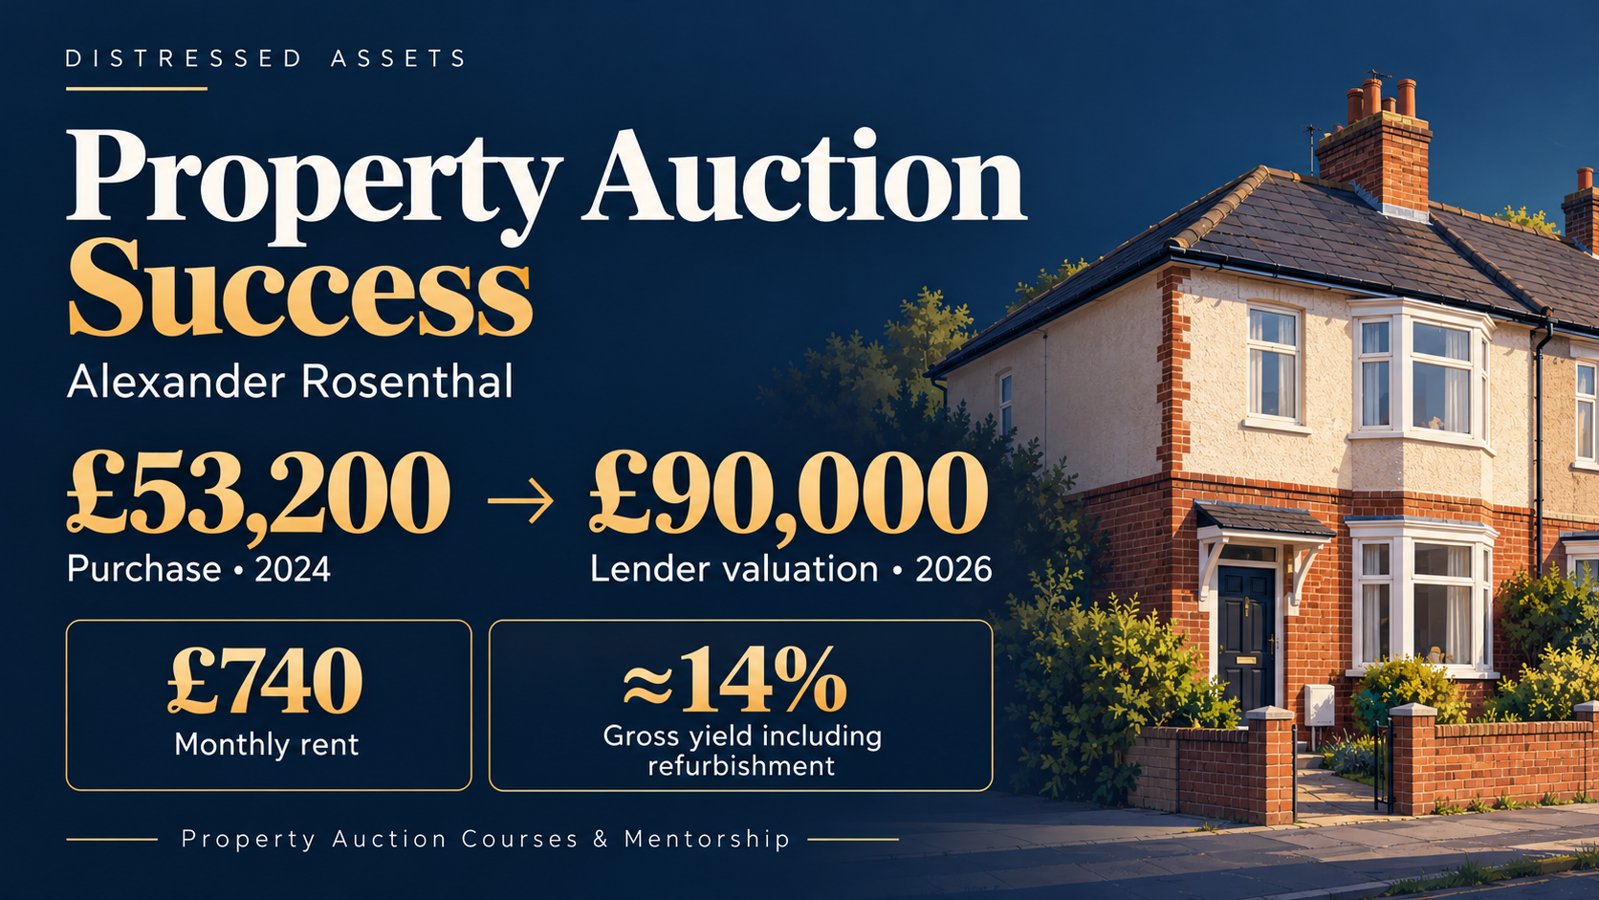
Alexander completed his purchase in 2024 for £53,200. After a refurbishment costing a little over £10,000, the two bedroom semi detached house now rents for £740 per month. In 2026, a lender valued it at £90,000.
Buying the right property before starting the refurbishment
The house already had a new roof and an EPC rating of C, according to Alexander. A modest refurbishment was required, rather than a wholesale redevelopment. The original Sutton Kersh listing describes a freehold house in Wallasey and records it as sold prior to auction in December 2023. Completion followed in 2024.
Alexander first met Dominic through a Distressed Assets property course in November 2023. Dominic subsequently sourced the property to match his requirements. The practical lesson for anyone researching property sourcing in Liverpool is to assess the purchase and the works as one investment decision.
What the refurbishment and rental figures show
| Measure | Amount |
|---|---|
| Purchase price | £53,200 |
| Refurbishment expenditure | Just over £10,000 |
| Purchase plus refurbishment | Just over £63,200 |
| Lender valuation in 2026 | £90,000 |
| Monthly rent | £740 |
| Annual gross rent | £8,880 |
| Gross yield on purchase price | 16.69% |
| Gross yield including refurbishment | Just under 14.05% |
The more useful yield for assessing this project includes the refurbishment. Dividing £8,880 annual rent by £63,200 gives 14.05%. As the works cost slightly more than £10,000, the actual figure is a little lower: approximately 14% gross before purchase costs and running expenses.
The £90,000 valuation is £36,800 above the purchase price. However, that difference is not all profit or value created by the building work. Refurbishment, buying costs and finance must be accounted for, and a lender valuation is not a completed sale.
How much original capital remains after refinancing?
At 75% loan to value, a £90,000 valuation supports a mortgage of £67,500. Compared with the combined purchase and refurbishment expenditure of just over £63,200, this is enough to recover that capital and release just under £4,300 more, before other costs.
Any existing borrowing is repaid from the refinance proceeds, and purchase costs, finance charges and refinancing fees reduce the surplus. The released money is mortgage borrowing, not realised profit. Alexander retains the property and its rental income, alongside the responsibility for the mortgage and ongoing expenses.
A plan that connects sourcing, refurbishment and letting
For a rental investment, the budget should reflect the property’s condition, the local tenant market and the likely finished value. Spending more does not automatically produce a proportionate increase in rent or valuation. Before committing, bring together the proposed works, contingency, achievable rent, comparable sales and financing options.
This is why our approach to property refurbishment in Liverpool and Wirral sits alongside sourcing and preparation for letting. The finished property needs to work as a home for tenants and as an investment for its owner.
“A big thank you to Dominic, Claire, Josh and the team for their expert advice, enthusiasm, and for guiding me every step of the way.”
Alexander Rosenthal
Planning your next property investment
If you are considering a refurbishment project in Liverpool, Merseyside or Wirral, start with the full cost of the investment and a realistic plan for the property once the work is complete.
Explore our property sourcing service, speak to us about refurbishment support, or discuss your plans with Dominic Farrell.
Contact Tuna Fish Property or call 0151 705 9055 to discuss your next investment.