Liverpool property investment · Case study
BRRR in Liverpool: a £75,000 purchase and £120,000 valuation
A property on Methuen Street, Liverpool L15, was purchased prior to auction for £75,000. Our subsequent update reported a £120,000 valuation for refinancing, 8 months later, without renovation. The starting price was central to the result.
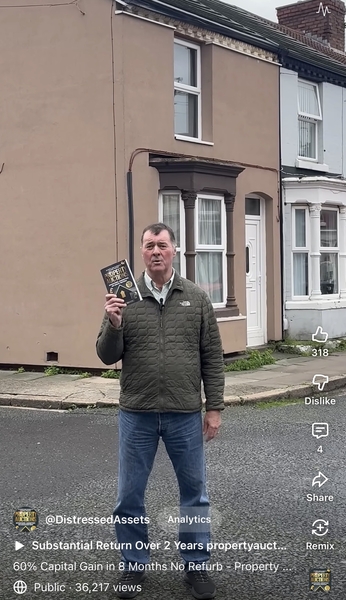
The Methuen Street purchase
Our November 2025 update recorded a house bought prior to auction for £75,000, with no renovation required. The subsequent refinance was reported at a property valuation of £120,000 after 8 months.
That is a £45,000 difference, equal to 60% of the original purchase price. The distinction matters: it is an increase between the purchase price and a reported mortgage valuation. It is not a completed sale, a £45,000 cash profit or confirmation of how much the lender advanced.
The original update also referred to a property marketed in the same street. An asking price can provide context, but completed sales and the lender’s assessment are more useful when testing a refinancing plan.
Watch the original Methuen Street video →
The investment lesson: buying at a well supported price can create room for costs, borrowing and valuation uncertainty. Renovation is useful when the evidence shows that the work is needed or adds sufficient value.
Why the purchase matters in a BRRR strategy
BRRR means buy, refurbish, refinance and rent. Investors often concentrate on the refurbishment because it is the most visible stage. However, the initial purchase determines how much money is committed before a contractor starts work.
A sound house bought at an attractive price may suit a rental strategy with relatively little work. Another property may need substantial renovation costs before it can be let or accepted by a mortgage lender. Compare both routes using the total investment, likely rent and time required.
Ask what each proposed improvement achieves. Essential safety work, repairs and measures that help a home let well belong in the budget. An expensive cosmetic specification needs its own justification. Our guide to BRRR property investment in Liverpool explains how the stages fit together.
A valuation and a mortgage advance are different figures
A lender uses its valuation alongside its lending criteria. The amount available can also depend on rent, the borrower, the property and the lender’s approach to a recent purchase. A broker should assess the proposed purchase and refinance before you commit.
For illustration only, a loan at 75% of a £120,000 valuation would be £90,000. At a £100,000 valuation, the same percentage would produce £75,000. These are calculations, not the recorded mortgage advance for Methuen Street or an offer of finance.
| Assumed valuation | Calculation | Illustrative loan |
|---|---|---|
| £120,000 | £120,000 × 75% | £90,000 |
| £100,000 | £100,000 × 75% | £75,000 |
The money released to you would depend on any existing debt that must be repaid and the costs deducted at completion. Compare that net amount with all the cash you have invested, including acquisition costs, finance and works. Keep a separate reserve for the property after refinancing.
MoneyHelper’s guide to buy to let mortgages explains why rental income and lender criteria matter to the borrowing available.
What to check before buying for a refinance
- Value the property as it stands. Use relevant completed sales and adjust for condition, size, tenure and location.
- Confirm what needs doing. Arrange an inspection and appropriate professional advice. A presentable interior does not establish the condition of the roof, structure or services.
- Build a complete cost schedule. Include taxes, auction charges, legal fees, finance, insurance, renovation costs and a contingency.
- Test the rental position. Obtain a realistic local rental assessment and allow for management, maintenance, empty periods and other running costs.
- Plan for a lower valuation or delay. Establish how you would hold the property and meet borrowing costs if the refinance is smaller or later than expected.
A disciplined investor should be comfortable with the fallback plan as well as the preferred outcome. That is particularly relevant if short term borrowing is funding the initial purchase.
Applying the lesson to your Liverpool property search
Our Property Sourcing Liverpool service considers the purchase, likely income and practical ownership costs together. We look at opportunities through auctions, receivers and other distressed situations against your own brief.
Explore our property sourcing track record for further examples. Each reflects a particular property and transaction; your own proposal needs its own assessment.
Your questions answered
Does every BRRR property need a refurbishment?
The property and your strategy determine the work required. This historical example was reported as needing no renovation. Other purchases may need substantial work before they can be rented or refinanced.
Does a higher valuation mean all my money comes back?
It depends on the mortgage advance, existing debt, fees and total cash invested. A valuation is one input into the calculation, and the lender still has to approve the borrowing.
Sources and case record
Adapted from our Original Methuen Street case study, 16 November 2025. Current guidance is linked beside the relevant discussion. Updated 12 October 2026.
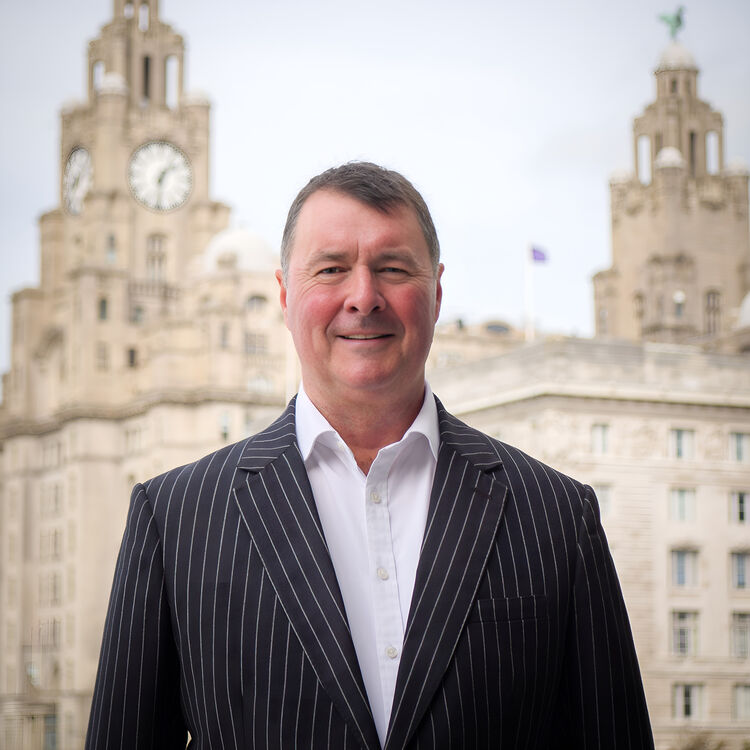
About Dominic Farrell
Dominic Farrell is a director of Tuna Fish Property, author of Property Auctions: Repossessions, Bankruptcies and Bargain Properties (4th edition) and host of The Property Auctions Podcast. His work combines property investment, sourcing and auction education.
He delivers The Property Auction Professional Mentorship through Distressed Assets.
Start your next investment with the purchase price
Discuss your budget, rental objectives and refinancing plans with Dominic Farrell and the Tuna Fish Property team. We can help you assess opportunities in Liverpool, Merseyside and Wirral.
This is a historical case study. Figures reflect the published account and do not guarantee another investor’s outcome. Acquisition costs, works, finance, tax and running costs affect the overall return.